GO2bank: Mobile banking

Screenshots
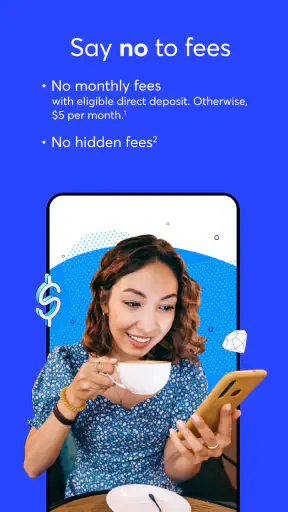
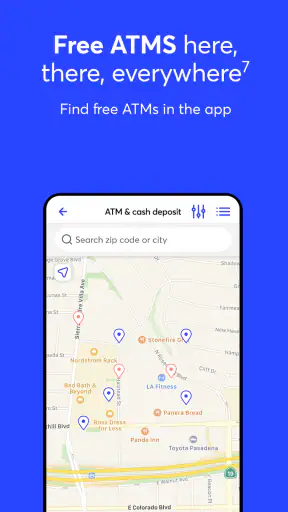
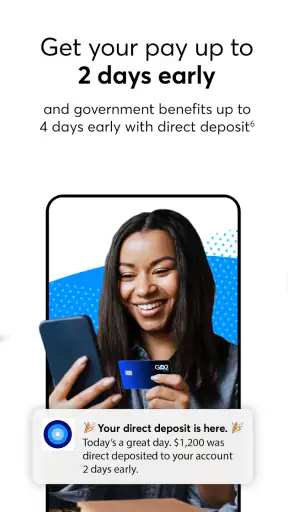
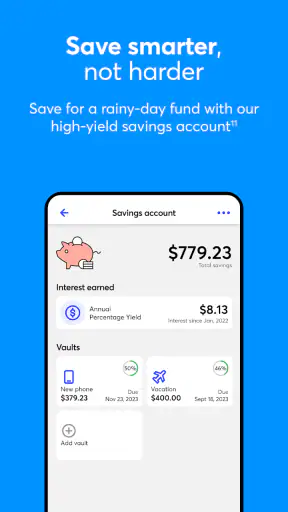
Details
- Rating
- 15.96K reviews
- Version
- 3.2.0
- Developer
- Green Dot
Analysis by Norviv
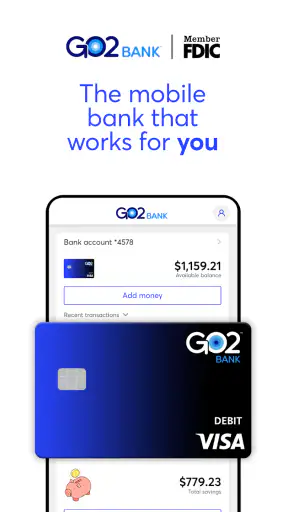
I approached GO2bank: Mobile banking as the kind of finance app someone might install when they want a straightforward way to manage everyday money from a phone. Developed by Green Dot, it is free to download, aimed at Everyone, and presents itself as a mobile bank rather than simply a budgeting tool or payment wallet. That distinction matters: the useful question is not whether it looks polished in a quick glance, but whether it fits the way you receive, spend, and monitor money.
My overall impression is positive, with an important qualification. The app can be convenient for routine banking tasks, especially when I want to check activity without visiting a branch or opening a desktop site. At the same time, finance apps are less forgiving than entertainment apps. A delayed screen, an unsuccessful sign-in, or a verification step can feel much more serious when I am trying to confirm a payment. The best way to judge this app is therefore to look closely at setup, recovery, and the situations where the problem may not be inside the app at all.
Where people usually get stuck
The first friction point is often not a missing feature but the expectation that a mobile bank should behave like a simple social or shopping app. Banking access normally depends on account details, identity checks, security controls, and a stable connection. If one part of that chain is incomplete, the screen may not move forward in the way a user expects. I found it more useful to treat the initial setup as a financial access process rather than a casual registration form.
That mindset also helps with sign-in problems. Before repeatedly entering credentials, I would check whether the phone is connected reliably and whether the information is being entered exactly as registered. Repeated attempts can create more confusion, particularly when a user is unsure whether the issue is a mistyped detail, a temporary connection problem, or a security check that has not completed.
A second common sticking point is misunderstanding what an account screen is showing. A transaction may appear under activity without meaning that every part of the underlying payment process has fully settled. Likewise, a balance is not always the same thing as money that can be spent immediately in every situation. I would read the labels and transaction status carefully before assuming that a displayed amount explains the final result.
This is one reason I prefer using the app for deliberate checks instead of constantly refreshing it. If I am waiting for a payment or deposit to appear, repeatedly reopening the same screen rarely provides better information. I would first note what action I took, when I took it, and what the app actually shows. That small record makes it easier to distinguish a display delay from a genuine account issue.
The app has a strong public footprint, with an average rating of 4.4 from roughly 105 thousand ratings and more than 5 million installs. Those figures suggest that it is familiar to a large audience, but they do not remove the need for careful setup. A popular banking app can still be a poor fit for someone whose needs depend on a particular branch service, a specialized financial product, or highly detailed money-management tools.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Why the first session deserves patience
When I test a finance app, I avoid making the first session my only evaluation. The opening experience tells me whether I can get access, but the more important test is whether I can return later and quickly answer practical questions: What money is available? What recently happened? Is a payment recorded? Can I find the setting or support path I need?
GO2bank is most appealing when those questions are part of a simple routine. For example, imagine being paid and wanting to check the account before buying groceries, then reviewing the activity after a recurring bill is charged. A mobile banking app is valuable here because it puts those checks in the same place. The benefit is not excitement; it is reducing the number of steps between a real-life money decision and the information needed to make it.
Where I would be more cautious is during a time-sensitive transaction. If a payment appears uncertain, I would not immediately repeat it just because the first attempt is not visible. Duplicating a payment can create a bigger problem than waiting briefly or confirming the status through the appropriate support route. The app is useful for observing account activity, but observation and authorization are not always the same thing.
Setup checks that prevent avoidable trouble
The cleanest setup begins with a phone that is ready for a financial app: a current connection, enough available storage for normal operation, and the operating system supported by the application. The listed minimum is iOS or Android version 9, so users on very old devices should check compatibility before planning to rely on it. I would also install the current release shown for the app, version 3.2.0, rather than judging the experience from an outdated copy.
After installation, I would use the same personal details consistently. Small differences in names, addresses, or contact information can make verification harder when a financial service needs to match the account holder. I would avoid rushing through screens simply to reach the home view. In banking, the details entered during setup can affect how easily an account is recovered later.
Another practical check is notification behavior. If the phone suppresses alerts, a user may miss an important sign-in prompt or account update and then assume the service is not responding. I would review the phone’s notification settings and make sure the app is not being restricted by a battery-saving mode that stops background activity. This is not a guarantee that every alert will arrive instantly, but it removes a common source of uncertainty.
I would also make a habit of using the official app store listing and the developer name, Green Dot, when installing or updating. That is a simple safety habit for any financial application. Avoiding unofficial copies and not sharing sign-in information through messages or calls protects the account in ways that no interface feature can replace.
The age rating of Everyone makes the app broadly accessible from a store-classification perspective, but that should not be confused with financial suitability for every household. A younger or inexperienced user may still need guidance about account security, spending decisions, and what to do when a transaction looks unfamiliar. The rating describes access suitability, not personal financial readiness.
Make the app easier to use before you need it
I recommend opening the app during a calm moment and learning where the main balance, recent activity, account controls, and help options are located. This is a small but valuable preparation step. When a transaction is urgent, familiarity reduces the temptation to tap randomly, repeat an action, or overlook a status message.
A useful workflow is to review activity after a planned purchase and compare the entry with the receipt or confirmation from the merchant. That does not require constant monitoring. It simply creates a reliable habit for spotting mistakes early. If something does not match, I would collect the relevant details before contacting support: the date, merchant description, amount, and what the app displays.
I would not use a public or shared device for account access, and I would avoid saving sensitive details where someone else can see them. These are ordinary precautions, but they matter more here than in most app categories. A smooth login is not worth weakening account security.
Recovering a workflow when something goes wrong
When the app does not load correctly, I start with the least disruptive checks. I confirm the connection, close and reopen the app, and try again without repeatedly submitting the same action. If the problem continues, I check whether the phone has pending system or app updates and restart the device. These steps sound basic, but they separate a temporary session problem from an account-specific issue.
If the app opens but information looks stale, I avoid assuming that the money itself has disappeared. I compare the visible activity with the timing of the transaction and any confirmation received elsewhere. A delayed display can be frustrating, but making another payment before understanding the first one can lead to duplicate charges. The safer workflow is to pause, document what happened, and use the app’s available support path if the status remains unclear.
Sign-in recovery deserves the same caution. I would use the in-app or official recovery process rather than following instructions from an unsolicited message. If a recovery code or verification step is involved, I would enter it only in the legitimate app flow and never disclose it to another person. This is a practical distinction that many users overlook when they are worried about losing access.
For an unfamiliar transaction, my first step would be to inspect the details rather than immediately deleting the app or changing unrelated settings. I would check whether the merchant name is recognizable under a different description and whether the amount corresponds to a recent purchase or recurring charge. If it still looks wrong, I would contact the service through an official channel and preserve the evidence needed to explain the issue.
One non-obvious advantage of keeping a simple personal record is that it improves support conversations. Writing down the exact sequence—what I attempted, what appeared, and what happened afterward—prevents vague reports such as “the app is broken.” It also helps reveal whether the issue occurs only with one transaction, only on one device, or every time I open the account.
When reinstalling helps and when it does not
Reinstalling can sometimes clear a damaged local session, but I would not treat it as the first answer to every banking problem. Removing an app does not reverse a transfer, cancel a payment, or repair an account-level verification issue. Before reinstalling, I would make sure I know how to sign in again and that I can complete any required recovery steps.
If the same problem returns immediately after a clean installation, that is a useful clue. It suggests looking beyond cached app data and checking account status, device compatibility, connection quality, or service support. This is where many users waste time: they repeat technical fixes for what is actually a transaction or account question.
The app’s current version is 3.2.0, and keeping software current is sensible, but an update should not be used as an excuse to ignore a suspicious account event. Technical maintenance and financial investigation are separate tasks. I would handle the account concern first, then deal with updating or reinstalling in a controlled way.
When the app is not the cause
Mobile banking sits between several systems. The app may display information, but merchants, payment networks, account processing, the phone, and the internet connection can all affect what I see. If a card purchase is declined, that does not automatically prove the app caused it. The same applies when a merchant has not yet completed its side of a transaction or when a connection drops during a request.
A useful test is to identify the boundary of the problem. If the app cannot open at all, I start with the device and connection. If it opens but one transaction is unclear, I focus on the transaction details and timing. If several functions fail across different attempts, I consider account access or a broader service issue and use official support rather than continuing to guess.
This distinction is especially important for people comparing GO2bank with a traditional bank app. A conventional bank may offer broader account products, branch assistance, or more established tools for complex financial planning. GO2bank can be the more convenient choice for someone who prioritizes phone-based access and a focused everyday banking routine. It is less compelling for a user who wants investing, extensive loan management, or a single dashboard combining many financial institutions.
Compared with a payment wallet, the difference is even clearer. A wallet is often built around paying merchants or moving money between services, while a mobile bank is intended to be the place where account activity is managed. I would choose a wallet for quick checkout convenience and this app when I want a banking relationship in one dedicated application. Some people may use both, but they should not assume that one substitutes perfectly for the other.
I would also skip it if my priority is highly advanced budgeting analysis. The app’s appeal is practical access, not replacing a specialist budgeting or accounting system. Someone who needs custom categories, deep reporting, or detailed household forecasting may be happier pairing their bank with a dedicated finance tool, provided they are comfortable with the privacy and security implications of doing so.
Who will get the most from it
I see the strongest fit for people who want a mobile-first way to check everyday banking activity, keep an eye on spending, and handle routine account decisions without depending on a desktop browser. It can also suit someone who is comfortable troubleshooting basic phone issues and who prefers a focused interface over a large financial-services ecosystem.
I would be more hesitant to recommend it as the only financial tool for someone with complicated banking needs, frequent cash-handling requirements, or a strong preference for in-person help. The right choice depends less on the app’s download price—it is free—and more on whether its mobile-centered approach matches the user’s habits and expectations.
Because the app is rated Everyone, families may be tempted to treat it as automatically suitable for any user. I would still discuss safe sign-in habits, suspicious activity, and the difference between checking a balance and approving a transaction. Financial confidence comes from understanding those distinctions, not simply from having an app installed.
My practical verdict after using it
GO2bank: Mobile banking is a credible everyday finance app with a clear use case: putting routine banking access in a phone-based workflow. Green Dot has built a product that is most useful when I need quick visibility into account activity and prefer not to manage ordinary tasks through a traditional desktop experience. Its broad adoption and 4.4 average rating indicate that many users find that approach worthwhile.
My recommendation comes with a practical rule: set it up carefully, learn the account screens before an urgent payment, and treat unclear transactions as financial questions rather than merely app glitches. That approach prevents the most damaging mistakes, especially repeated payments and unsafe recovery attempts.
The limitations are meaningful. A mobile bank cannot solve a merchant-side delay, a weak connection, an account verification problem, or a need for sophisticated financial planning. Users who expect every balance update to be immediate may become frustrated, and people who want branch-based support or a broad collection of financial products should compare alternatives first.
For my own use, I would recommend it to a friend who wants a focused mobile banking experience and is willing to pay attention to security and transaction status. I would not present it as a universal replacement for every bank, wallet, or budgeting service. The best reason to choose it is dependable everyday access, not the promise of eliminating every banking complication.
With that expectation, the app makes sense: free, accessible to a broad audience, supported on devices running version 9 or later, and maintained as a dedicated finance product. It works best when used deliberately—checking activity, confirming details, and following a measured recovery process when something looks wrong. That is a less flashy conclusion than calling it perfect, but it is the honest reason I would consider installing it.
Frequently Asked Questions
01What is GO2bank, and who can use the app?
GO2bank is a mobile banking app designed for everyday money management, including checking account access, direct deposit, bill payments, money transfers, and debit card control. It is primarily intended for eligible users in the United States. Before downloading, check the current availability requirements, identity verification rules, age restrictions, and whether the service supports your state and personal circumstances.
02Is GO2bank safe for mobile banking and payments?
GO2bank includes common security features such as login protection, account monitoring, transaction notifications, and the ability to manage or lock a debit card through the app. However, no banking service is completely risk-free. Use the official app store, keep your device updated, avoid sharing passwords or verification codes, and contact customer support immediately if you notice suspicious activity.
03What fees should I expect when using GO2bank?
GO2bank may charge fees depending on how you use the account. Possible costs can include monthly service fees, out-of-network ATM withdrawals, cash deposits, expedited services, or certain transfer options. Some fees may be waived when specific requirements are met, such as qualifying direct deposit. Review the latest fee schedule carefully before opening or actively using the account.
04Can I deposit money, receive direct deposit, and withdraw cash with GO2bank?
The app supports several common ways to fund and access an account, including eligible direct deposits, transfers, cash deposits at participating retailers, and ATM withdrawals with the associated debit card. Availability, limits, processing times, and fees can vary by transaction type and location. Confirm the current terms in the app before relying on GO2bank for regular paycheck or cash access.
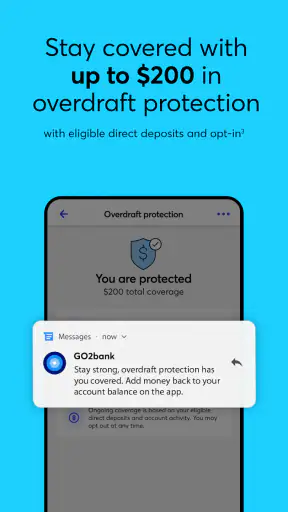
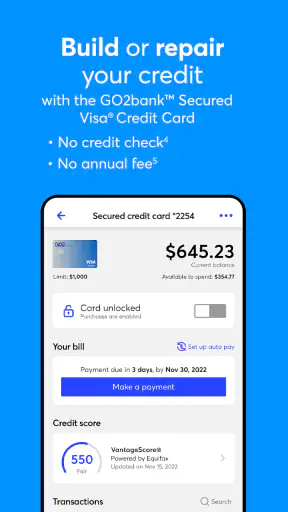
05Does GO2bank offer overdraft protection or credit-building features?
GO2bank may provide optional features intended to help eligible customers manage overdrafts or build credit, but these services are not automatically available to everyone and may involve enrollment requirements, limits, or additional terms. They should not be treated as unlimited borrowing. Read the eligibility conditions, repayment rules, reporting details, and applicable fees before activating any optional feature.


